Bienvenue · WelcomeEN / FR
Les Brokers

A Guide for American Buyers

Buying Property in Paris

The process, phase by phase: how it actually works here, held up against how it works at home.

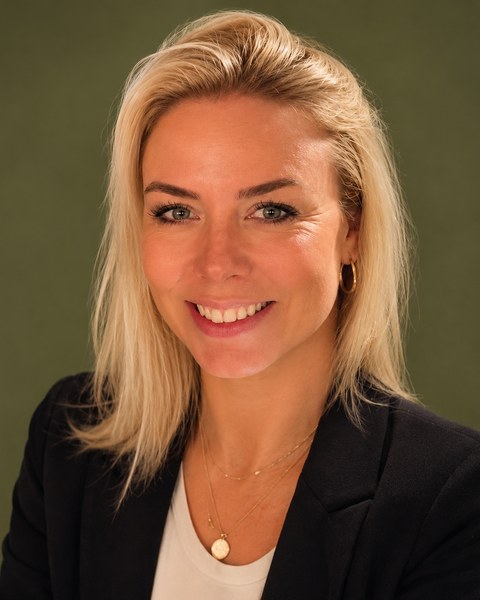
Helena Hermanns

Written by

Helena Hermanns

Illustration: a writing desk by an open window overlooking the Seine and Île Saint-Louis, with an envelope, a fountain pen, an espresso and a set of keys

Over eight years I’ve walked many American clients through buying property in Paris. The paperwork looks unfamiliar on day one, but the shape of the process isn’t complicated once someone lays it out for you, so that’s what this page does: phase by phase, set directly against the version you already know from home.

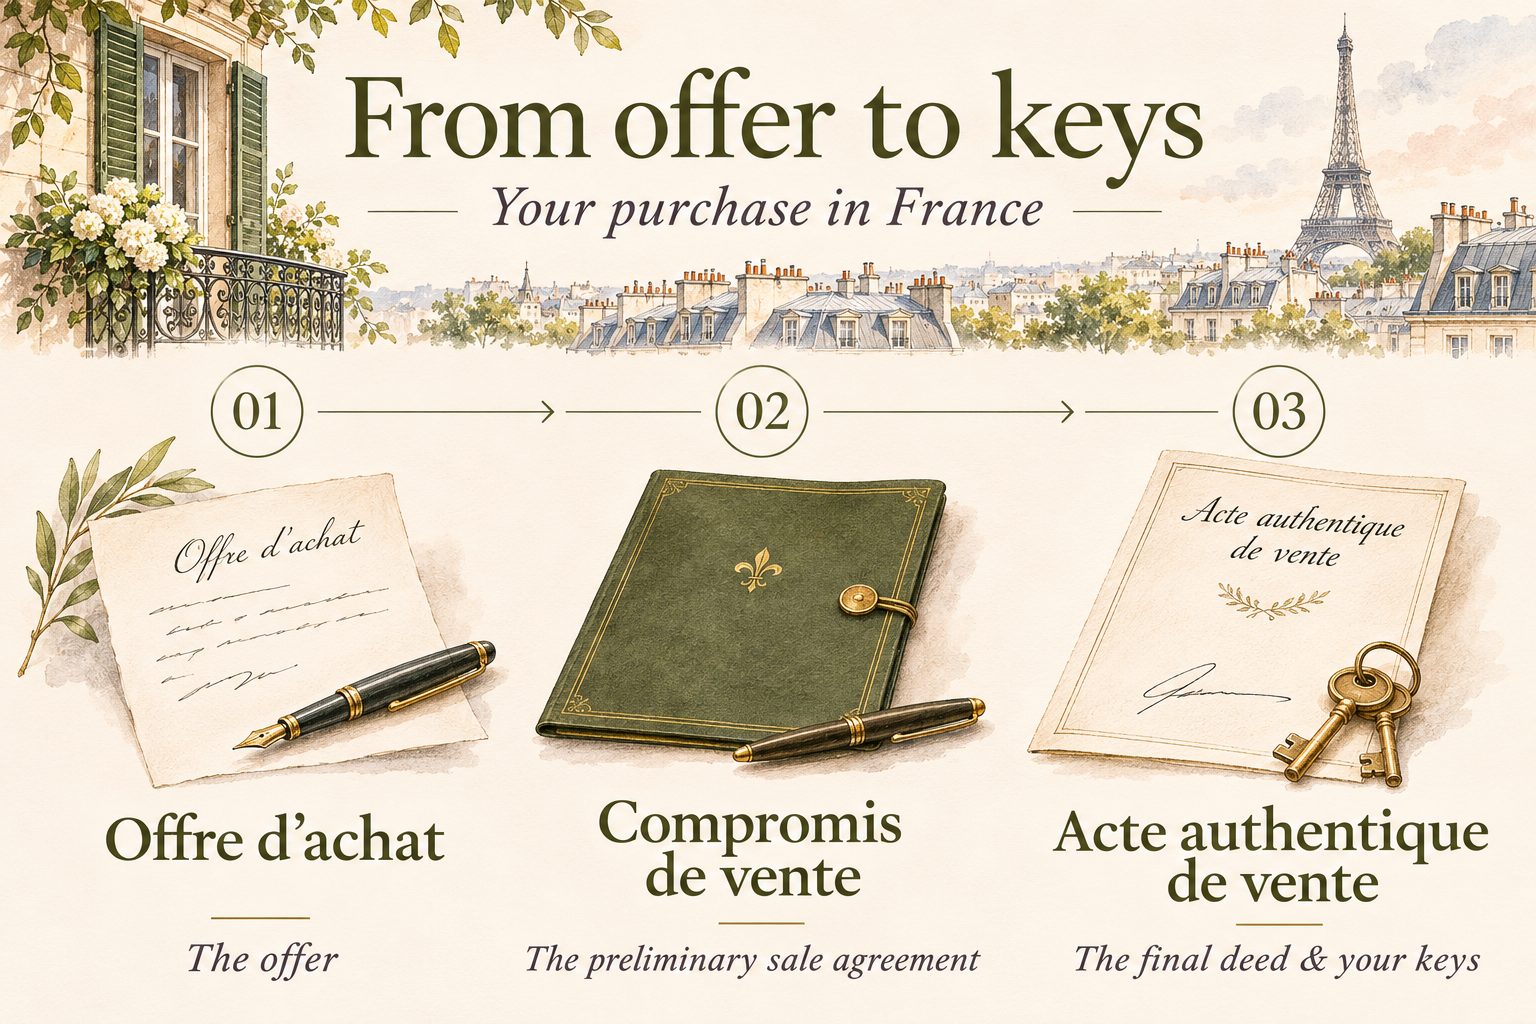
From offer to keys: 01 Offre d’achat (the offer), 02 Compromis de vente (the preliminary sale agreement), 03 Acte authentique de vente (the final deed and your keys)

Two playbooks, same goal

Five phases, side by side

Five phases, each compared side by side, plus what I actually tell clients when we get there.

01 · Finding & Choosing Your Agent

USIn the U.S.

  • Buyer’s agent works only for you
  • Searches a shared MLS
  • Commission split with seller’s agent: no direct cost to you

FRIn France

  • Listings traditionally held by one agency; shared listings now growing
  • Your own property finder (chasseur d’appartement): you sign an exclusive search mandate (mandat de recherche), and your agent works only for you: on- and off-market search, visits, due diligence and negotiation. The fee is 3% of the purchase price, and nothing is due until the final deed is signed.
  • Or, an inter-agency selection: properties shared between agencies, where the commission is split, at no added cost to you
“Say an apartment is listed at €1.5 million. Once we’ve done the due diligence and know the market, we can often negotiate around 3% or more off the price. It’s never guaranteed, but when it happens, a dedicated agent costs you almost nothing extra. So I tell clients to expect to pay close to the asking price, with their own agent and our whole network included.”
Helena

N.B. If you’ve already started your search and given your criteria to other agencies, we won’t be able to share commission with those agencies.
02 · Finding & Evaluating the Property

USIn the U.S.

  • Agent pulls comps
  • Buyer tours, then an inspection contingency later in the process

FRIn France

  • Full building file requested upfront: co-ownership minutes, reserve fund, past works
  • Diagnostics report reviewed (energy, lead, asbestos, etc.)
  • With recent comparable sales, we build our own price study, so we know where to position your offer before you bid
“We price the offer knowing exactly what’s really been happening in that building, not just what’s on paper.”
Helena

03 · The Offer & Proof of Funds

USIn the U.S.

  • Offer often still negotiable on both sides
  • Financing contingencies common
  • Earnest money typically modest

FRIn France

  • Accepted offer is hard for the seller to retract
  • Low risk for you, high risk for the seller
  • Proof of funds required: France monitors for money laundering
“Once a French seller accepts your offer, they can’t easily walk away — that’s the opposite of how it feels back home.”
Helena

04 · The Preliminary Sales Agreement

USIn the U.S.

  • Purchase agreement with contingencies
  • Earnest money, then an inspection period

FRIn France

  • Compromis de vente, negotiated by both notaires
  • Fully transparent, so there are no surprises later: price, conditions, diagnostics and building documents are all agreed here. Only the notaire’s final checks and the final accounts (taxes, split of charges) are left for the deed
  • 5–10% deposit due at signing
  • 10-day cooling-off period, then the deposit is forfeited if you withdraw
“After the ten-day cooling-off period, you start carrying real risk right alongside the seller.”
Helena

05 · The Final Signing

USIn the U.S.

  • Closing walkthrough, then a single closing day

FRIn France

  • Choice of two signings (compromis, then acte de vente weeks later) or one combined signing
  • A final walkthrough a few days before (visite de conformité): the apartment is usually empty by now, so we check nothing has been damaged, photograph the meters and move electricity and gas into your name
  • Final step reviews the same documents, plus accounting: quarterly charges, property tax, refunds
“If you’re sure about the property, doing it all in one signing saves a trip and adds very little risk.”
Helena

P.S. Then we open the champagne. In Paris, it would be rude not to.

In clients’ words

“I would recommend her to anyone who needs knowledgeable hard working guidance in finding their dream property.”
Mark Reeves · on Helena · Google reviews
“Helena and her team got it righter than right… Use no other agent.”
Jolliffe · on Helena · Google reviews
“Very happy with the excellent service”
Brynja Valdimars · on Helena · Google reviews

A quick glossary

The words you’ll hear

The French terms you’ll run into, and the closest American shorthand for each.

French termClosest US equivalentWhat it means here
NotaireClosing attorney / escrow officerNeutral, state-appointed official who authenticates the sale. You’re entitled to your own, at no added cost.
Compromis de ventePurchase & sale agreementThe binding preliminary contract; starts the 10-day cooling-off period.
Chasseur d’appartementBuyer’s agentA licensed agent who works only for the buyer, under a written search mandate (mandat de recherche). Paid only once the purchase completes.
Délai de rétractationCooling-off period10 calendar days after signing the compromis during which you may withdraw freely.
Acte de venteDeed / closing documentThe final deed, signed in person (or by proxy) at the notaire’s office.
Visite de conformitéFinal walkthroughA last visit a few days before the deed, to check the property’s condition and read the meters.
SyndicHOA / management companyManages the shared building; sets and collects co-ownership charges.
Taxe foncièreProperty taxAnnual property tax, billed once a year, generally in the fall.
Multirisque habitationHomeowners insuranceInsurance for the unit itself, separate from the building’s master policy.
FATCAUS reporting lawRequires French banks to report American account holders to the IRS. That’s why some banks are slower to onboard US clients.

Meanwhile

Money, banking & insurance

These run in parallel with the phases above, and are worth starting early.

  1. Currency exchange

    Lock in a USD → EUR rate early with a specialist, rather than leaving it to your bank the day funds are due.

    Talk to our currency specialist
  2. French bank account

    Not always urgent, but simplifies paying fees and charges. Expect extra paperwork as an American, due to FATCA reporting.

  3. Financing

    If using a mortgage, French banks want an offer in hand before final signing, so plan for extra weeks versus a US closing timeline.

    Talk to our mortgage specialist
  4. Home insurance

    Your own multirisque habitation policy, separate from the building’s master policy, should be in place at or just before signing.

    Talk to our insurance specialist
  5. After signing

    Set up utilities, register with the syndic, and expect an annual property tax bill (taxe foncière) each fall.

At a glance

What it costs

The figures most American buyers ask about first. Rates are set locally and change; your notaire confirms the exact amount before you sign.

  • Notaire fees (frais de notaire)

    Around 7–8% of the price for an older property, and about 2–3% for a new build. Most of it is transfer tax paid to the state and the city; the notaire’s own fee is a small, regulated part.

  • Agency fees

    Set out in writing in the mandate before any search or visit. In an advertised listing, the price shows whether fees are included and who pays them.

  • Co-ownership charges

    Paid quarterly to the syndic for the building’s upkeep, staff and insurance. Ask for the last three years of accounts before you offer.

  • Property tax & insurance

    Taxe foncière once a year, plus your own home insurance. Both continue whether or not you live there.

Before you sign

Owning, tax & renting out

A short overview, not tax or legal advice. These choices are easier to make before the compromis than after the deed.

  • Whose name goes on the deed

    Buying in your own name, jointly, or through a French property company (SCI) changes how the property is taxed and passed on. Decide before you sign.

  • Wealth tax on property (IFI)

    If your net real estate in France is worth more than €1.3 million on 1 January, you owe the annual IFI, even as a non-resident. Property outside France isn’t counted.

  • Rental income

    Rent from a Paris property is taxed in France first. The US–France tax treaty is there to stop you paying twice, so your French and US accountants should talk to each other.

  • Short-term letting

    In Paris, a main residence can be let to tourists for 90 nights a year at most, with a registration number. A second home or pied-à-terre needs a change-of-use authorisation, which is rarely practical. Furnished lets of a year or more are the usual route.

  • Energy rating (DPE)

    Homes rated G can no longer be newly let, and F-rated homes follow from 2028. If you plan to rent, check the rating before you offer.

  • Inheritance

    French succession rules can apply to property in France, whatever your will says at home. Worth a conversation before you choose how to hold title.

Talk to our tax specialist

Last reviewed November 2026. Rules and rates change; check with your notaire and advisers before relying on any figure.

The one thing this page can’t give you

My actual contacts

The bilingual notaire. The currency specialist who locks in a rate. The banker who doesn’t blink at FATCA paperwork. The insurer who picks up the phone. Those come from a conversation, not a web page, and I’m happy to make the introduction.

Book a discovery call Message Helena

Or call me+33 6 43 12 90 33

Tell me where you are in the process and I’ll pick up from there.

Put me in touch with

A short note and they will get back to you directly.

Your details go to this specialist only, with Helena Hermanns and Kash Hussain of Les Brokers in copy.